

Your California Cannabis Bank
California Cannabis Banking
Herring Bank offers 2026-ready cannabis banking solutions for California CRBs, blending regulatory expertise with advanced tools to ensure growth and compliance.
California Cannabis Banking Solutions: Secure, Compliant Services for CRBs
Herring Bank – Your Trusted Partner in Navigating Cannabis Finance
As the April 2026 federal move of state-licensed medical marijuana to Schedule III reshapes the financial landscape, Herring Bank remains California’s leading cannabis-friendly banking partner, offering tailored solutions to empower licensed cannabis businesses. With deep expertise in evolving state and federal regulations, we provide the tools to streamline operations, ensure compliance, and fuel growth in this high-stakes industry.
Why Herring Bank Stands Out in 2026
Regulatory Mastery
Navigate California’s complex cannabis banking terrain with confidence. Our team specializes in:
- SAFE Act compliance (despite federal delays)
- DCC licensing alignment for cultivators, dispensaries, and distributors
Comprehensive Financial Services
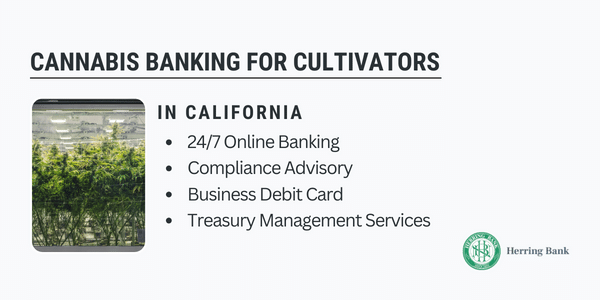
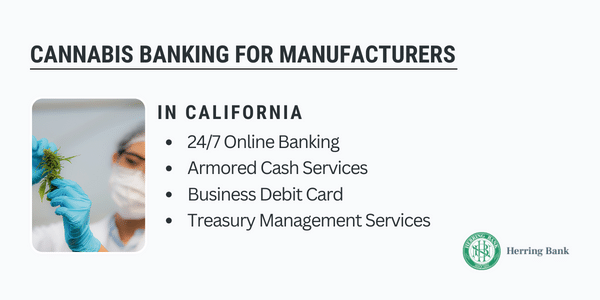
- Business Accounts: High-limit checking/savings with 24/7 digital banking
- Cash Solutions: Armored transport, cash pickup/delivery, and deposit automation
- Growth Support: ACH payments, payroll management, and commercial real estate loans up to 50% LTV
Addressing 2026’s Biggest Challenges
- Unlicensed Market Pressure
Our cash management systems help licensed operators compete with the unlicensed market by reducing cash-handling risk and the time spent on manual deposits. - Local Licensing Delays
Access our pre-licensing financial toolkit—a roadmap for securing permits in restrictive counties like Orange or San Diego. - Tax Burdens
Since April 28, 2026, activity under a state medical cannabis license is in Schedule III and no longer subject to Section 280E, while adult-use sales remain Schedule I and 280E still applies. Cannabis CPAs can help allocate income and expenses between medical and adult-use activity and prepare for pending IRS guidance.
FDIC Insurance
- FDIC-insured accounts
Serving All Major Markets: Los Angeles, San Francisco, Sacramento, San Diego, Fresno & beyond.
Ready to Bank with Confidence?
📞 Call Now: Nationwide +1-877-873-0079 | Local +1-719-470-2340
Marijuana-Friendly Banking in California
Cannabis-friendly banks have emerged as indispensable allies for California’s cannabis-related businesses (CRBs), bridging the gap between federal restrictions and the state’s thriving legal market. These specialized financial institutions, including pioneers like Herring Bank, deliver more than just basic checking and savings accounts—they offer tailored solutions that address the unique operational hurdles faced by CRBs. From digital banking platforms that simplify cash flow management to compliance tools that align with California’s evolving cannabis laws, these banks provide the infrastructure needed to legitimize and scale operations in a high-risk sector.
Beyond foundational services, cannabis-friendly banks like Herring Bank streamline critical financial workflows for CRBs. Secure electronic payment processing, online bill pay/tax payment systems, and direct deposit payroll services minimize cash dependency while ensuring adherence to state and federal reporting standards. This proactive support not only enhances operational efficiency but also fortifies long-term financial stability in an industry where traditional banking remains fraught with barriers.
The influence of these institutions extends far beyond day-to-day banking. By developing cannabis-specific financial products and advocating for fairer federal policies, forward-thinking banks are reshaping the economic landscape of California’s cannabis sector. Their commitment to understanding the industry’s nuances—from seed-to-sale tracking to environmental compliance—fuels innovation and fosters trust. As the market matures, this collaboration between CRBs and cannabis-friendly banks will remain vital to balancing rapid growth with regulatory accountability, ensuring the sector’s legitimacy and sustainability for years to come.
Banking Solutions for California Cannabis Related Businesses
2026 Cannabis Banking in California: Laws, Licensing and Market Status
California is the largest licensed cannabis market in the country and one of the most complex places to run a cannabis business. Medical cannabis has been legal since voters passed the Compassionate Use Act (Proposition 215) in 1996, adult use was approved through Proposition 64 in 2016, and licensed adult-use sales began in January 2018. Nearly a decade later, California cannabis banking is shaped by layered state and local taxes, two levels of licensing, a large unlicensed market, a new hemp law and the first real federal changes in decades.
California’s Cannabis Regulator and Licensing System
The Department of Cannabis Control (DCC) licenses and regulates every commercial cannabis cultivator, manufacturer, distributor, testing laboratory, retailer, microbusiness and event organizer in the state under the Medicinal and Adult-Use Cannabis Regulation and Safety Act (Business and Professions Code, Division 10). Key rules for operators:
- Dual licensing: every business needs a DCC license and local authorization. Cities and counties decide whether to allow storefront retail, cultivation or manufacturing, so access to legal storefronts is still uneven across the state.
- License volume: the DCC’s fiscal year 2024-25 supplemental report (published March 2026) counted 7,912 active annual licenses and 376 remaining provisional licenses. The largest concentrations are in the City of Los Angeles (907), Sacramento (314) and Oakland (236) and, among counties, Humboldt (986), Santa Barbara (651) and Mendocino (554).
- Consumption lounges: AB 1775, effective January 1, 2025, lets cities allow licensed consumption lounges to sell non-cannabis food and drinks and host live events.
- Track and trace: licensees report inventory and transfers through the California Cannabis Track-and-Trace system, which banks use to reconcile deposits with reported sales.
California Cannabis Taxes and Market Status in 2026
Retail cannabis sales carry a 15% state cannabis excise tax, plus state and local sales tax and any city or county cannabis business tax. The excise rate temporarily rose to 19% for July through September 2025 and returned to 15% on October 1, 2025 after Gov. Newsom signed AB 564. According to the California Department of Tax and Fee Administration, licensed retailers generated $261.7 million in state cannabis tax revenue in the second quarter of 2026, after $249.8 million in the first quarter, and nearly $8.4 billion since January 2018.
The licensed market still competes with a large illicit one. The DCC’s market outlook estimates that about 11.4 million pounds of unlicensed cannabis are produced in California each year, compared with about 1.4 million pounds of licensed production. Price pressure, local bans and tax costs keep margins tight, which makes efficient cash handling and low-cost electronic payments more valuable for licensed operators.
California Hemp and Intoxicating Cannabinoid Rules
On October 2, 2025, Gov. Gavin Newsom signed AB 8, which moves California toward regulating all intoxicating cannabinoid products, whether derived from cannabis or hemp, under a single framework. The law keeps intoxicating hemp products in licensed dispensaries for qualifying adults, stops the sale of synthetic cannabinoid products and inhalable hemp products, and gives state and local agencies new tools against unlawful cannabinoid products. The federal hemp redefinition passed in November 2025, now scheduled to take effect for most provisions on December 11, 2026, tightens THC limits nationwide. Herring Bank offers dedicated hemp banking and CBD banking for compliant operators.
Federal Changes That Affect California Cannabis Businesses
Effective April 28, 2026, the Department of Justice moved FDA-approved marijuana products and marijuana subject to a qualifying state medical license from Schedule I to Schedule III. For California licensees, that means activity under a medical license is expected to fall outside Section 280E going forward, while adult-use sales remain in Schedule I and subject to 280E, so dual medical and adult-use operators need clean separation of revenue and expenses. The DEA’s separate proceeding to reschedule all marijuana held hearings from June 29 to July 15, 2026, and the chief administrative law judge stayed it on September 29, 2026.
Banking law has not changed. The SAFE Banking Act of 2026 (S. 4942 and H.R. 9471, cosponsored by California Rep. Lou Correa) was introduced in June 2026 and remains in committee, so banks still serve California cannabis businesses under FinCEN’s guidance for marijuana-related businesses, with enhanced due diligence, ongoing monitoring and Suspicious Activity Report (SAR) filing.
What This Means for Banking a Cannabis Business in California
California’s market is mature, competitive and heavily taxed, and every dollar has to be documented for the DCC, the CDTFA and local tax offices. Herring Bank works with California dispensaries, cultivators, manufacturers, distributors, delivery services and testing labs to open compliant business accounts, document DCC and local licensing for BSA/AML review, manage cash with pickup and delivery through our preferred armored courier, and run payroll, ACH, wires and electronic tax payments, including state excise, sales and local cannabis taxes. Ready to talk about California cannabis banking? Call 877-873-0079 or request a call back.
Frequently Asked Questions
Can dispensaries use banks?
Yes, dispensaries can use banks like Herring Bank for their financial services, despite the challenges CRBs face in accessing banking services.
What types of cannabis companies do you support?
Herring Bank extends its banking services to a diverse range of cannabis enterprises including Dispensaries, Cultivation operations, Manufacturing firms, Armored Transportation services, among others.
What is the banking Act for cannabis?
The SAFE Banking Act of 2026 (S.4942 in the Senate, H.R.9471 in the House), introduced in June 2026 and still in committee, would provide “safe harbor” protections to financial institutions, increasing accessibility to banking, lending, and insurance services for the marijuana industry.
What are the benefits of partnering with specialized financial institutions?
Partnering with specialized financial institutions offers cannabis businesses growth opportunities, enhanced banking efficiency, and strong compliance and regulatory support. This can help improve the overall financial management and stability of the business.
What Cities do you serve? Where can cannabis businesses bank in California?
Herring Bank offers Cannabis Banking Services to the following cities: San Jose, Fresno, Sacramento, Long Beach, Bakersfield, Anaheim, Stockton, Riverside, Irvine, Santa Ana, Chula Vista, Fremont, Santa Clarita, San Bernardino, Modesto, Fontana CA. The Bank has developed an extensive network of armored couriers to securely manage cash deposits for cannabis companies.


